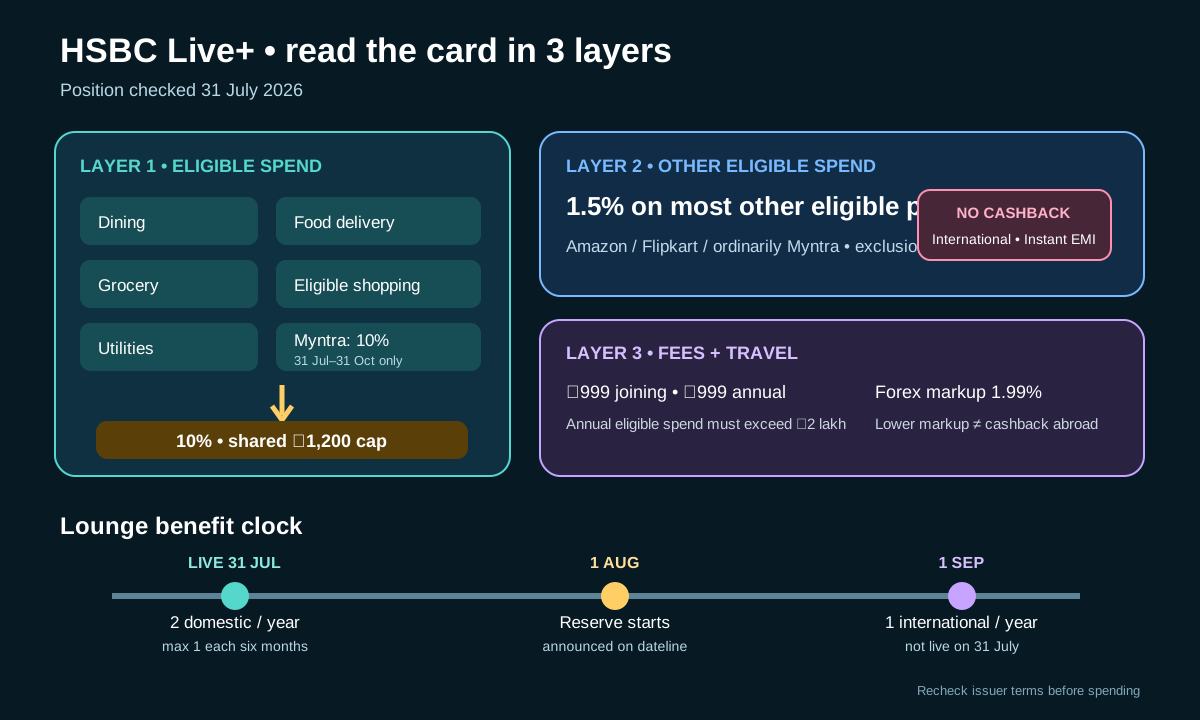
HSBC Live+ is a cashback card with a simple headline and several important boundaries. Dining, food delivery, grocery, eligible shopping and utilities can earn 10%; most other eligible spend earns 1.5%. The accelerated categories share one ₹1,200 cap, so the card does not return 10% indefinitely. Merchant exceptions, transaction exclusions and benefit start dates are part of the product, not footnotes to ignore.
Freshness check: Checked 31 July 2026. The current service guide is dated July 2026. The Myntra launch offer became effective on 31 July 2026 and expires after 31 October 2026. The Live+ Reserve is announced but starts on 1 August 2026, while the complimentary international lounge visit starts on 1 September 2026. Neither later benefit should be called live on this dateline. Recheck HSBC’s current terms before applying or concentrating spend.
The card in one table
| Feature | Position checked on 31 July 2026 | Practical reading |
|---|---|---|
| Joining fee | ₹999 plus applicable taxes | Paid entry cost; separate from annual fee |
| Annual fee | ₹999 plus applicable taxes | Reversed when eligible annual spend exceeds ₹2 lakh, according to HSBC |
| Accelerated cashback | 10% on dining, food delivery, grocery, eligible shopping and utilities | Combined ₹1,200 cap; ₹12,000 of fully eligible spend can fill it |
| Other cashback | 1.5% on most other eligible spend | HSBC describes this as unlimited, subject to exclusions |
| Amazon/Flipkart/Myntra | Ordinarily 1.5% | Myntra temporarily receives 10% from 31 July through 31 October 2026 within the same shared cap |
| International spend | No cashback under July 2026 guide | Forex markup is 1.99%; currency conversion and applicable taxes still matter |
| Instant EMI | No cashback | Treat EMI pricing and fees separately from the reward rate |
| Domestic lounge | Two visits per calendar year | Maximum one complimentary visit in each six-month period |
| International lounge | One visit annually from 1 September 2026 | Announced/upcoming on 31 July, not yet usable |
| Live+ Reserve | 1 August 2026 to 31 July 2027 | Announced/upcoming on the dateline; partner capacity and terms apply |
The fee-waiver wording deserves precision. HSBC says the relevant eligible annual spend must exceed ₹2,00,000. Spending exactly ₹2 lakh should not be presented as sufficient. The fee is charged and then reversed in a later statement on meeting the criterion, rather than never appearing. If this threshold influences retention, reconcile eligible primary and add-on spend against the card anniversary year and verify how refunds are treated.
How the ₹1,200 cap changes the headline
At 10%, ₹12,000 of qualifying accelerated spend produces ₹1,200. Once that shared ceiling is reached, further spend in those categories does not create more accelerated cashback for that period. HSBC’s product page uses “a month”, while the Myntra launch terms describe the combined ceiling per billing cycle; cardholders should check their statement communication for the operational period.
| Example monthly spend | Rate before cap | Cashback used in example |
|---|---|---|
| Dining ₹4,000 | 10% | ₹400 |
| Grocery ₹5,000 | 10% | ₹500 |
| Utilities ₹2,000 | 10% | ₹200 |
| Myntra ₹3,000 during launch offer | 10% | ₹100 remaining under shared cap, not ₹300 |
| Other eligible spend ₹20,000 | 1.5% | ₹300 |
| Total | — | ₹1,500 |
This illustration assumes all transactions are classified and eligible. It also shows why adding category percentages is misleading: Myntra does not receive a separate ₹1,200 promotional bucket. Readers who routinely exceed ₹12,000 across the accelerated basket should compare the effective return after the cap, using the cashback cap explainer.
Myntra is a temporary exception to the usual large-marketplace rule. Eligible Myntra website/app shopping earns 10% from 31 July to 31 October 2026, inclusive, and returns to 1.5% after the offer period under the published terms. Amazon and Flipkart continue at 1.5%. Cancelled, disputed, reversed or refunded Myntra transactions do not count, and add-on cards do not receive a separate offer allowance.
What changed from the legacy Cashback proposition
HSBC still hosts material for the older Cashback card. That material is useful for comparison, but it does not establish one universal migration date for every cardholder. HSBC has not published an official notice in the sources reviewed that supports claiming an exact Cashback-to-Live+ rename date.
| Term | Legacy Cashback material | Current Live+ material |
|---|---|---|
| 10% categories | Dining, food delivery, grocery | Adds eligible shopping and utilities |
| Accelerated ceiling | ₹1,000 per billing cycle | ₹1,200 a month; Myntra terms say shared per billing cycle |
| Forex markup | 3.5% | 1.99% |
| Domestic lounges | Four a year, one per quarter | Two a year, max one per six months |
| International lounge | Not listed | One a year effective 1 September 2026 |
| International cashback | Legacy guide included base treatment subject to exclusions | Removed under July 2026 Live+ guide |
| Instant EMI cashback | Legacy product material described cashback | Removed for Live+ Instant EMI |
The trade-off is therefore not a universal upgrade. Someone spending heavily on utilities and eligible shopping may value the expanded 10% basket and larger cap. Someone who used all four domestic lounge visits or relied on cashback abroad gives up meaningful benefits. The lower forex markup narrows transaction cost, but “1.99% markup” is not the same as zero total foreign-exchange cost.
Lounge access needs date and quota checks
On 31 July, the live domestic allowance is two complimentary visits per calendar year with at most one in each six-month period. Two trips in January and February cannot both use the allocation. Add-on cardholders have separate domestic lounge eligibility under the published launch terms, but guest entry is not complimentary. Access remains subject to a participating lounge, capacity, presentation requirements and a small validation authorisation.
The international visit is effective only from 1 September 2026. A product-page summary that says “two domestic and one international” compresses different start dates. Before travel, use the lounge-denial checklist and confirm the then-current Visa list and HSBC terms.
Who may find the structure useful
The clearest fit is a cardholder whose regular eligible dining, food-delivery, grocery, utility and shopping total reaches much—but not vastly more than—₹12,000 in the relevant period, who can naturally exceed the annual fee-waiver threshold, and who accepts the lounge reduction. A person with predominantly international, Instant EMI, fuel or excluded spend should calculate from the applicable rate, not the 10% headline.
This is not a universally best card and this review is not financial or tax advice. Compare the card with existing no-fee options, repayment habits and actual merchant mix. Interest from carrying a balance can exceed cashback quickly; rewards are not a reason to spend more or pay late.
Frequently asked questions
Does every shopping transaction earn 10%?
No. Eligibility and merchant classification matter. Amazon and Flipkart ordinarily earn 1.5%; Myntra earns 10% only during the 31 July–31 October 2026 launch offer, then ordinarily returns to 1.5%.
Is the ₹1,200 cap separate for dining, grocery and Myntra?
No. It is combined across all eligible 10% categories, including temporary Myntra cashback.
Is the international lounge visit available on 31 July 2026?
No. HSBC states that it becomes effective on 1 September 2026.
Does spending ₹2 lakh waive the annual fee?
The published wording says eligible spend must exceed ₹2 lakh. Do not rely on exactly ₹2,00,000.
Does lower forex markup mean international purchases earn cashback?
No. The July 2026 Live+ guide says cashback is no longer earned on international spend, while the forex markup is 1.99%.
Primary sources
- HSBC Live+ product page
- HSBC Live+ credit card service guide
- HSBC credit-card terms and tariff
- HSBC legacy Cashback product page
- HSBC legacy Cashback service guide
- HSBC Myntra launch-offer terms
- HSBC Live+ Reserve terms
Official HSBC material was checked and paraphrased on 31 July 2026. Product, merchant and lounge terms can change; verify the current issuer documents before spending.