Source check: 9 September 2026. Announcement date: 30 July 2026. Commencement: 1 October 2026. The new deadline is not yet operative on the date of this report.
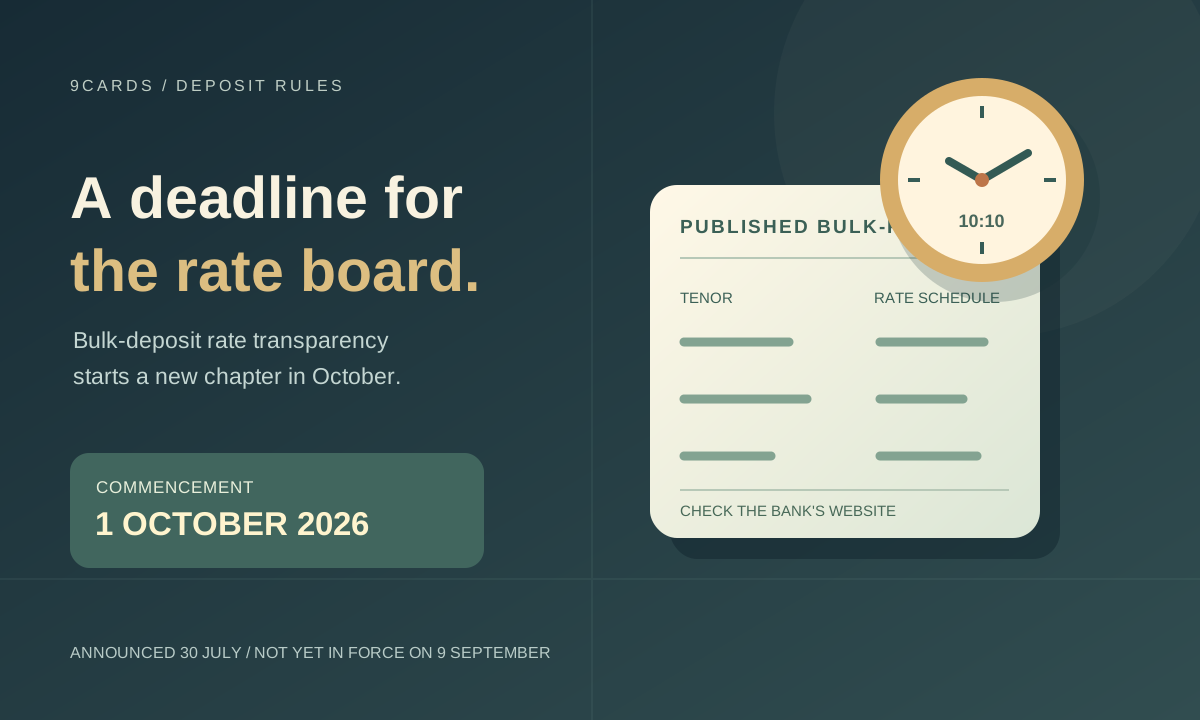
RBI has set a specific daily publication time for bulk fixed-deposit rates. From 1 October 2026, banks covered by the cited amendment must disclose those rates at 10:00 a.m. each business day, with ten minutes' grace: no later than 10:10 a.m.
This is not a fresh September announcement. The amendment was issued on 30 July 2026, and the upcoming commencement is why it matters now. It is also not a promise that deposit rates will rise when the clock reaches 10:10.
The change gives large depositors a clearer reference point for checking a published rate schedule rather than relying only on an individual branch quotation.
Which deposits are we discussing?
Under the commercial-bank directions cited here, a bulk deposit is a single rupee term deposit of INR 3 crore or more. That threshold should not be applied indiscriminately to every category of bank or treated as the definition of every customer's total banking relationship.
The word "single" matters. The definition is not simply a statement that a customer with total assets above INR 3 crore has made a bulk deposit. Product structure and the applicable bank category still need to be checked.
| Question | Position in the cited rules |
|---|---|
| When was the amendment announced? | 30 July 2026 |
| When does the new deadline start? | 1 October 2026 |
| When must bulk rates be disclosed? | 10:00 a.m. on each business day, with grace until 10:10 a.m. |
| Where is the schedule disclosed? | On the bank's website in advance |
| Commercial-bank bulk threshold | A single rupee term deposit of INR 3 crore or more |
| Does RBI prescribe a new customer interest rate? | No; the amendment concerns disclosure and the pricing framework |
Most ordinary retail FDs are below this commercial-bank bulk threshold. A headline claiming that every small FD gets a new rate at 10 a.m. would therefore misstate the development.
Publication and uniform treatment
The amended provision requires deposit rates, including bulk-deposit rates, to follow a schedule disclosed in advance on the bank's website. It also expressly includes bulk deposits in the rule against discriminatory rates for similar amounts accepted on the same date, subject to the permitted differentiation framework.
The practical value is comparability. If two quotations differ, a depositor has a published schedule and a defined pricing framework against which to ask what accounts for the difference.
It does not follow that every deposit must earn the same rate. Tenor, amount and other permissible distinctions remain relevant. Comparing unlike deposits can produce a difference that the rule was never intended to prohibit.
A permitted distinction based on liquidity treatment
The amendment permits differentiation in domestic bulk-deposit rates based on the applicable Liquidity Coverage Ratio run-off rate of the deposit or funding category. It also adds that permitted distinction to the section covering non-resident rupee deposits.
This is a regulatory liquidity classification used by banks. It is not a new fee deducted from a customer's interest and should not be described as a personal credit-score penalty.
For a depositor, the useful question is which published category the bank has applied and why. It would be misleading to assume that the new uniformity wording abolishes every classification-based difference while ignoring the amendment's express permission for this one.
What a quotation should make clear
For a placement after the commencement date, compare the bank's applicable published schedule with the quotation for the same date, amount, tenor and deposit category. Keep a dated copy of the offer or placement confirmation so that a later website revision does not become the only record available.
That is a documentation step, not a recommendation to concentrate savings in a larger deposit. A rate-publication rule does not change a depositor's need to consider liquidity, early-withdrawal conditions, concentration and any applicable protection limits.
Nor does the amendment promise a better return from one bank than another. The article does not rank banks by current bulk rates because those rate cards were not independently compared for this report.
The October boundary
RBI issued a corresponding small-finance-bank amendment with the same commencement date and morning publication deadline. That supports the breadth of the disclosure change, but readers must still use the directions applicable to their particular institution rather than transplant every commercial-bank definition.
As of 9 September, the new deadline is still forthcoming. A bank's current publication practice should not be called a breach of an October requirement merely because the amendment has already been announced.
The concrete development is a scheduled improvement in rate transparency: a defined website disclosure obligation and a daily deadline for bulk-deposit rates. It is neither a new customer charge nor a guaranteed increase in deposit income.